

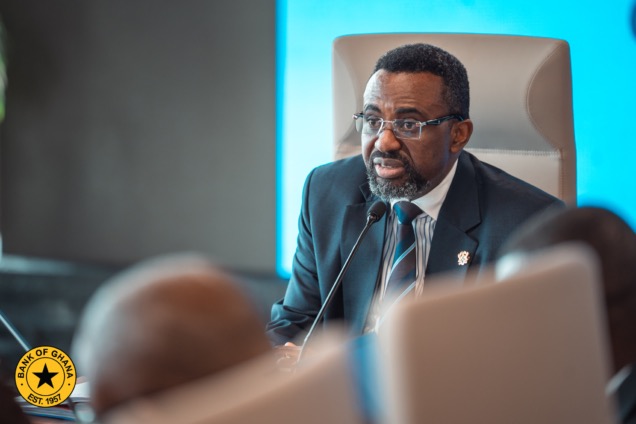
Financial institutions and authorised users conducted 25,932,946 enquiries for credit application appraisals, loan recoveries and Know Your Customer (KYC) purposes in 2025, the Bank of Ghana has disclosed in its 2025 Credit Reporting Report, marking a 12.12% decline from the 29,496,440 enquiries recorded in 2024.
The decline, according to the central bank, was largely driven by a reduction in traditional loan enquiries, which had historically been the primary driver of enquiry volumes. However, the broader upward trend in credit bureau usage affirms the growing importance of the credit referencing system in lenders’ credit administration processes.
“This significant increase is mainly due to growth in digital loans provided by various lenders,” the report noted, pointing to a structural shift in Ghana’s credit market.
Banks Dominate Credit Enquiries
Commercial banks remained the dominant users of the credit referencing system, accounting for 86.28% of total enquiries in 2025—a position the sector has maintained over the years. Microfinance and microcredit institutions accounted for 8.47% of total enquiries, a slight decrease from 8.82% recorded in 2024, while searches among savings and loan companies and other institutions also declined.
The composition of enquiries reveals that credit application appraisals constituted 87.21% of total enquiries, followed by credit bureau searches at 10% and loan recoveries at 3%.
A particularly notable development was the surge in financial institutions’ use of credit bureau services for credit monitoring purposes, which increased by 199.71% compared to the previous year. The Bank of Ghana attributed this sharp rise to the growth in mobile money loans and payroll lending, reflecting how digital credit products are reshaping how lenders monitor borrower behaviour in real time.
The Digital Lending Revolution Behind the Numbers
The decline in overall enquiries masks a fundamental transformation in Ghana’s credit landscape. While traditional loan enquiries fell, digital lending platforms have exploded in scale and reach.
Ghana’s mobile money transactions surpassed GH¢1.9 trillion by June 2025, up from GH¢571 billion in 2019, with more than 22 million active mobile money accounts now in existence—compared to just 18 million traditional bank accounts. This means that for a growing share of Ghanaians, a mobile wallet has replaced a bank branch entirely.
Interoperable mobile money transaction values rose 87% between December 2024 and December 2025, reaching GH¢5.8 billion, while transaction volumes climbed 45% to approximately 29 million. MTN’s QwikLoan alone disbursed over GH¢1 billion within its first 18 months of operation, while buy-now-pay-later schemes and nano-loans proliferate across the market.
Only 16% of Ghanaians are currently covered by credit bureaus, but digital lenders are creating what analysts describe as “reputational collateral”—using mobile transaction histories as a proxy for creditworthiness that could eventually unlock cheaper, longer-term lending for millions of previously excluded borrowers. Ghana has already ranked first globally in the 2024 GSMA Mobile Money Regulatory Index with a score of 95.06% and recently achieved a 96% rate of financial service access, surpassing its national target of 85%.
The Evolution of Ghana’s Credit Reporting System
Ghana’s credit reporting framework has come a long way since the enactment of the Credit Reporting Act, 2007 (Act 726), which established the legal basis for credit bureaus and the Credit Reporting System (CRS). The CRS was designed to promote fair credit pricing, responsible borrowing and lending practices, to reduce default rates and improve access to credit.
Since the law’s passage, the Bank of Ghana has licensed three credit bureaus: XDS Data Ghana Limited, Dun & Bradstreet Credit Bureau Limited, and My Credit Score Limited. These bureaus collect and maintain credit histories, process credit-related data, and deliver credit reports to financial institutions.
XDS Data Ghana has historically been the dominant bureau in the banking subsector, handling 57% of bank enquiries, while Hudson Price Data Solutions and XDS each recorded 46% of enquiries in the non-bank financial institution subsector. Hudson Price’s licence was revoked by the Bank of Ghana in November 2022 for non-compliance.
The regulatory framework has evolved significantly. In 2021, the Bank of Ghana expanded the list of institutions required to participate in the CRS to include telecommunications companies, utility firms, retailers, mobile money operators, fintechs, and government agencies providing credit to MSMEs. Under current regulations, eligible participants must provide credit information on their customers to all licensed credit bureaus within 72 hours of entering into a credit agreement, and must obtain credit reports on prospective customers before extending credit.
The Bank of Ghana has also issued a notice on the retention of credit information, clarifying that credit facilities with outstanding balances beyond maturity shall not be deleted from a borrower’s credit report until full repayment, while fully paid-off facilities shall not be retained beyond six years from the date of closure.
International Support and Reform Efforts
The International Finance Corporation (IFC) is supporting Ghana’s credit reporting strengthening through a project designed to fortify the legal and institutional foundations of the framework. The project, with an estimated budget of $520,000 running from January 2024 to June 2027, provides technical assistance to the Bank of Ghana and key players in the credit information sharing ecosystem, including credit bureaus and financial institutions.
A key focus of the project is enhancing the use of alternative data and analytics by credit bureaus to improve access to credit for micro and small enterprises, which are predominantly informal and lack a credit history.
The Bank of Ghana has also undertaken a comprehensive diagnostic assessment of Ghana’s Credit Reference Bureaus to benchmark operational and technological capabilities against international best practices. The assessment identified structural and capacity gaps, particularly in ICT and data analytics, which are being addressed to enhance credit scoring and establish a centralised data hub to standardise credit data submission.
New Credit Scoring System and Diaspora Access
In November 2024, then-Vice President Dr. Mahamudu Bawumia launched MyCreditScore, a new credit scoring system aimed at improving access to finance by providing timely and accurate information on the debt profile and repayment history of borrowers. The system, which uses a credit score range of 250-900, is expected to significantly improve lending efficiency, lower default rates, and unlock credit for underserved populations who may lack traditional collateral.
The Bank of Ghana has also approved a cross-border credit reporting service to help Ghanaians abroad build credit history, a move expected to significantly improve the financial inclusion of the diaspora and allow them to establish a financial foothold in their new home countries.
The Road Ahead
The figures from the 2025 Credit Reporting Report paint a picture of a credit market in transition. While overall enquiry volumes have declined from their 2024 peak, the underlying infrastructure of credit reporting is becoming more sophisticated and more widely used across different segments of the financial sector.
For Ghana’s lenders, the challenge remains balancing the expansion of credit to underserved segments—particularly SMEs, which account for approximately 70% of GDP and over 80% of employment—with prudent risk management. The Bank of Ghana’s ongoing reforms, supported by international partners, aim to strengthen the credit information ecosystem to make that balance achievable.
The report was prepared in line with Section 58 of the Credit Reporting Act, 2007 (Act 726), and presents a comprehensive overview of key developments in the CRS, statistical trends in credit enquiries and data submissions, the performance of credit bureaus, and the activities of financial institutions and Designated Data Providers (DDPs) during 2025.
The Bank of Ghana’s 2025 Credit Reporting Report is available on the central bank’s website.