

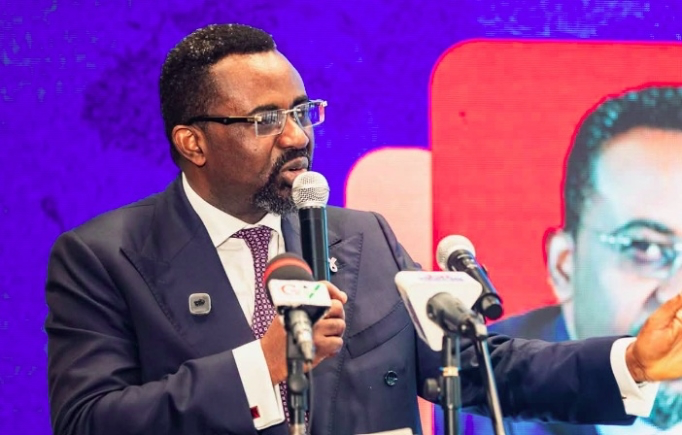
All 23 banks operating in Ghana have now met the central bank’s regulatory capital requirements, Bank of Ghana Governor Dr Johnson Pandit Asiama announced on Thursday, marking the completion of a recovery process that began after the 2022 Domestic Debt Exchange Programme (DDEP) triggered widespread capital shortfalls across the sector.
Speaking at the 43rd Annual General Meeting of the Ghana Association of Banks and the launch of the sixth edition of the GH Bankers’ Voice Magazine in Accra, Asiama said the 2022 audited financial statements had shown 13 banks in breach of regulatory capital requirements as a result of the economic crisis and financial asset impairments.
“Through the collective efforts of banks, shareholders, investors, the Association, Government and the Bank of Ghana, all 23 banks have now met the regulatory capital requirements. This is a significant achievement,” he said.
The governor, however, cautioned against complacency. “Restoring regulatory capital was only the beginning,” he said, adding that the focus must now shift to ensuring banks maintain capital commensurate with their risk profiles and build sufficient buffers to withstand future shocks.
From Crisis to Recovery: The DDEP Shock
The DDEP, introduced in December 2022 as part of Ghana’s efforts to restructure its domestic debt and secure International Monetary Fund support, required banks and other financial institutions to exchange existing government bonds for new ones with longer maturities and reduced interest rates. The programme placed significant strain on bank balance sheets and profitability at the time.
According to an estimate cited in academic research, the losses of 22 banks following the DDEP were estimated at GHS 7.3 billion in 2022, with private domestic banks and state-owned banks accounting for the bulk of those losses. Fitch Solutions noted that the DDEP minimised the profitability of Ghanaian banks.
But the crisis also forced a strategic reset. Farihan Alhassan, Managing Director of GCB Bank PLC, Ghana’s largest lender by assets, said in an April 2026 interview that the DDEP “forced us to think differently, to be a bit more clever with the customers,” adding that the challenges ultimately pushed banks to innovate and become more customer-focused.
Industry players have in recent months reported stronger earnings, improved asset quality, and renewed growth in lending as the sector recovers from the immediate shocks of the debt restructuring programme.
Sector Performance: Strong Headline Numbers
The banking sector’s recovery is reflected in broad improvements across key indicators. As at the end of August 2026, total banking sector assets had increased by 20.47 per cent to GH¢500.20 billion, compared with GH¢415.20 billion a year earlier.
The sector remains well capitalised, with the Capital Adequacy Ratio improving from 18.28 per cent to 19.10 per cent, significantly above the regulatory minimum of 13 per cent. Asset quality has also improved, with the Non-Performing Loans (NPL) ratio declining from 20.77 per cent in August 2025 to 15.66 per cent in August 2026.
The improvement in capital adequacy followed a difficult period. The sector’s capital adequacy ratio had fallen to 11.3 per cent at end-2023 before recovering to 14 per cent at end-2024 and 17.5 per cent by December 2025, even after adjusting for regulatory reliefs. The Bank of Ghana had allowed derecognition losses emanating from the debt exchange to be spread equally over four years, effective 2022, to cushion banks against the immediate impact.
Average lending rates have also declined significantly, falling to 15.9 per cent in August 2026 from 24.2 per cent a year earlier, while real private-sector credit growth increased to 29 per cent.
The NPL Deadline: A Hard Countdown
Despite the improvement in asset quality, the governor reminded banks of the requirement to reduce their NPL ratios to the prudential limit of 10 per cent by the end of December 2026, describing asset quality as one of the most important vulnerabilities within the banking sector.
With less than three months remaining, banks still need to cut their NPL ratio by 5.66 percentage points to meet the regulatory target. The Bank of Ghana has signalled that institutions exceeding 15 per cent will face immediate restrictions on dividend and bonus payments.
The scale of the problem is evident in earlier figures. According to the Bank of Ghana’s Financial Stability Review 2024, non-performing loans rose from 15 per cent of gross bank loans in 2020 to 22 per cent in December 2024. At that point, more than one-fifth of the banking sector’s total loan portfolio consisted of non-performing loans, with the deterioration in asset quality affecting banks’ profitability, liquidity and solvency.
The central bank issued a Notice on Non-Performing Loans in August 2025 to strengthen governance arrangements for credit risk management, establish prudential limits on NPLs and provide remedial measures in respect of wilful defaulters. Wilful loan defaulters now face a five-year credit ban under the new rules.
Asiama said banks must strengthen underwriting standards, credit administration, loan monitoring, restructuring practices, collateral management, write-offs and recovery processes, adding that increasing regulatory attention to NPLs represented a shift from simply provisioning for problem loans to ensuring that banks actively prevent, manage, recover and resolve problem assets.
The Bank of Ghana is also in the process of issuing a Directive on Credit Risk Management to complement the NPL Notice, covering credit origination, administration, monitoring, measurement and recovery. The new framework comes as private-sector lending continues to expand rapidly, with credit to the private sector growing by 35.5 per cent in August 2026, compared with 13.3 per cent a year earlier. The governor cautioned that this pace of credit expansion must be supported by appropriate underwriting standards and effective risk-management systems.
Liquidity: A New Prudential Benchmark
On liquidity, Asiama said the Bank was in the process of publishing the Liquidity Coverage Ratio (LCR) Directive, which would establish the prudential liquidity requirement for banks and mark an important milestone in strengthening liquidity regulation.
Under the proposed framework, banks would be required to maintain a Liquidity Coverage Ratio of at least 100 per cent, meaning they must hold enough high-quality liquid assets to cover total net cash outflows over a 30-day stress period. Level 2 assets would be capped at 40 per cent of high-quality liquid assets, while Level 2B assets would be limited to 15 per cent. The proposed directive is scheduled to take effect on September 1, 2027, with submissions on the exposure draft due by November 30, 2026.
The governor said the ratio should not be viewed as merely another regulatory figure but should form part of a broader liquidity risk-management culture supported by appropriate contingency funding arrangements, diversified funding sources and effective asset-liability management.
The Bank of Ghana has also strengthened its macroprudential stress-testing framework and has been engaging banks on the results of stress tests conducted under severe but plausible economic and financial scenarios. Institutions are expected to use the results to inform capital planning, liquidity management, risk appetite and strategic decision-making.
Business Model Analysis: From Compliance to Forward-Looking Supervision
The Bank of Ghana undertook a comprehensive thematic review of the viability and long-term sustainability of banks’ business models in 2025, examining funding structures, asset allocation patterns, earnings composition, and governance effectiveness under both baseline and stress scenarios.
Although the review affirmed that Ghana’s banking sector remains viable and profitable, it highlighted structural features that require closer regulatory monitoring, including a heavy reliance on net interest income, which accounts for approximately 68 per cent of industry profitability. Net interest margins narrowed from 14.2 per cent in December 2024 to 11.5 per cent by December 2025, following a reduction in the Monetary Policy Rate from 27 per cent to 18 per cent over the same period.
Financial intermediation also remains modest, with loans accounting for less than one-fifth of total industry assets. As of December 2025, total advances stood at GH¢111 billion against total assets of GH¢446.9 billion. Asset concentration in sovereign and central bank instruments remains elevated, reflecting banks’ preference in recent years for government securities over private sector lending.
The vulnerabilities identified have been shared with the respective institutions, and engagements with boards and senior management have commenced. The Bank intends to conduct a second round of Business Model Analysis next year.
Digitalisation, Cybersecurity and AI: A New Supervisory Frontier
The governor said cybersecurity, digital fraud, data protection, third-party dependencies, cloud computing and operational resilience were receiving increasing supervisory attention. Following the publication of the revised Cyber and Information Security Directive (CISD) 2026, launched in March, the Bank has continued to work closely with the Association and the industry to facilitate implementation.
The CISD 2026 brought fintech companies and payment service providers under mandatory cyber resilience obligations for the first time alongside traditional banks, and introduced governance frameworks for artificial intelligence, stricter cloud computing security protocols, and mandatory board-level accountability for cybersecurity. The Bank plans to undertake thematic reviews focusing on the directive’s implementation.
Boards and senior management should treat cybersecurity and operational resilience as core business risks and not simply as technology issues, Asiama said.
On artificial intelligence, the governor said the Bank was developing a Directive on the Use of Artificial Intelligence in the Financial Sector, which would seek to promote responsible experimentation and innovation while ensuring appropriate governance throughout the AI lifecycle. He noted that AI had the potential to improve credit assessment, fraud detection, customer service, risk management and operational efficiency, but also introduced new risks relating to data quality, model risk, cybersecurity and consumer protection.
The Road Ahead: “Stability Must Translate into Purposeful Intermediation”
Asiama framed the challenge ahead in stark terms. “The question before the industry is not whether the banking sector has recovered from the crisis that led to the Domestic Debt Exchange Programme and emerged more resilient, but whether enough is being done to preserve the gains and build a sector better equipped to withstand future shocks,” he said.
He emphasised that regulation alone cannot create a resilient banking sector. “The ultimate responsibility lies with boards, management and the institutions themselves to build strong risk cultures, sustainable business models and institutions that can serve customers through both good times and periods of stress.”
The ambition, he said, should be to build a banking sector “strong enough to absorb shocks, innovative enough to adapt to change and capable of financing Ghana’s long-term economic transformation”.
“Stability must now translate into purposeful intermediation,” the governor stressed, underscoring the central bank’s expectation that stronger balance sheets will support greater lending to productive sectors of the economy.