

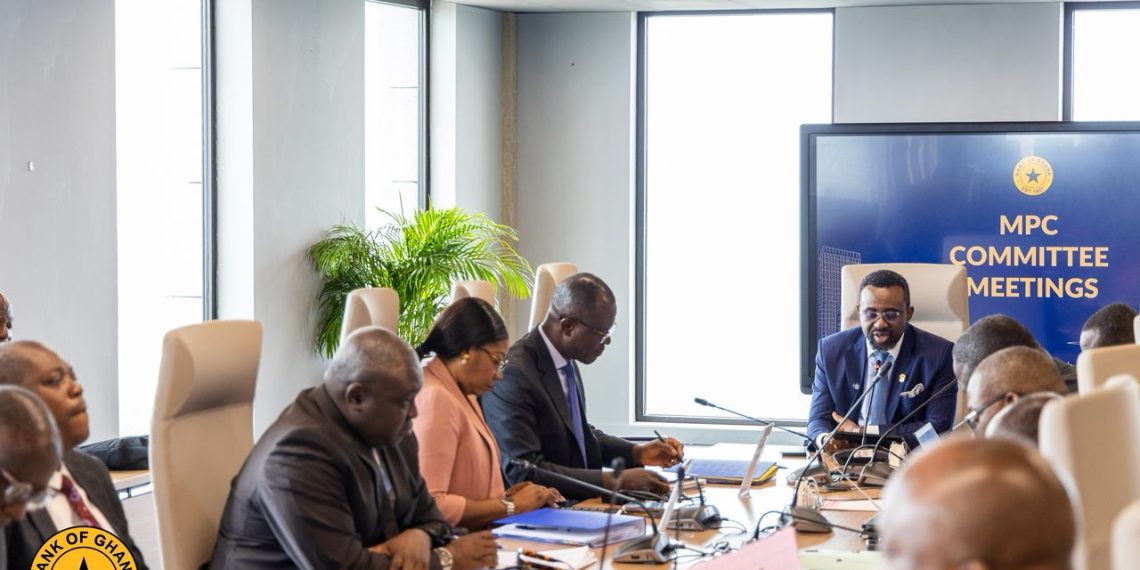
The Bank of Ghana (BoG) has moved to introduce its first-ever prudential liquidity benchmark for the banking sector, proposing a Liquidity Coverage Ratio (LCR) Directive that would require banks to hold enough high-quality liquid assets to survive a 30-day period of severe financial stress.
The central bank published the exposure draft on October 9, 2026, and has invited banks, industry stakeholders, and the general public to submit comments by November 30, 2026. Submissions are to be sent to bsdletters@bog.gov.gh, in line with the BoG’s Procedures for Issuance of Directives, 2020. The BoG has proposed September 1, 2027, as the effective date, with banks required to align their internal policies, processes, and systems by August 31, 2027.
What the Directive Proposes
Under the proposed framework, banks would be required to maintain a Liquidity Coverage Ratio of at least 100 per cent. This means their stock of eligible, unencumbered high-quality liquid assets (HQLA) must be sufficient to cover their total net cash outflows projected over the next 30 calendar days under prescribed stress conditions. The framework is designed to ensure that banks can continue meeting short-term obligations even when funding conditions tighten sharply.
The LCR would be calculated by dividing a bank’s stock of eligible HQLA by its total net cash outflows over the next 30 calendar days. Qualifying assets must be capable of being converted into cash quickly, with little or no loss of value, and must be free from restrictions that would prevent their use during a period of stress. The directive identifies cash, qualifying balances held with the Bank of Ghana, and eligible government securities among the assets that may qualify as HQLA.
The proposed framework places limits on the composition of the liquidity buffer. Level 2 assets would be capped at 40 per cent of the total stock of HQLA, while Level 2B assets would be limited to 15 per cent. Banks would also be required to assess potential cash outflows arising from deposit withdrawals, reduced access to wholesale funding, maturing financing obligations, and customers drawing on previously committed credit facilities. The draft further requires banks to conduct their own liquidity stress tests, including scenarios more severe than the minimum 30-day supervisory requirement.
Significance of the Reform
Governor Dr Johnson Pandit Asiama told bank chief executives on October 6 that the LCR would introduce the first prudential benchmark for banks’ liquidity. Speaking to the Ghana Association of Banks two days later, he emphasised that the ratio should become part of a broader liquidity risk culture in banks rather than merely another compliance figure. The directive would complement the Liquidity Risk Management and Liquidity Monitoring Tools directives already issued.
The proposal comes at a time when lending is accelerating sharply. Private-sector credit grew 35.5 per cent year-on-year in August 2026, up from 13.3 per cent a year earlier, while the average lending rate declined to 15.9 per cent from 24.2 per cent over the same period. Faster loan growth draws on the same funds banks would otherwise hold as liquid buffers. Dr Asiama cautioned that “this growth must be supported by sound underwriting standards and effective risk-management frameworks”.
Ghana’s banks have strengthened considerably since the 2022 debt crisis. The industry’s Capital Adequacy Ratio stood at 19.10 per cent at the end of August 2026, and non-performing loans fell to 15.66 per cent from 20.77 per cent a year earlier. Liquid assets to total deposits increased to 96.3 per cent at the end of December 2025 from 92.5 per cent a year earlier, while liquid assets to volatile funds rose to 151.8 per cent from 139.5 per cent. However, the NPL ratio remains well above the 10 per cent ceiling banks must meet by December 2026.
Complementary Credit Risk Reforms
The LCR directive forms part of a broader regulatory push to strengthen risk management across the banking sector. The BoG has also outlined a Credit Risk Management Directive to complement the Non-Performing Loan Notice issued in 2025. That directive will cover the full lending process, including credit origination, administration, monitoring, measurement, and recovery. Second Deputy Governor Mrs Matilda Asante-Asiedu explained that the directive aims to ensure regulated financial institutions “develop and implement appropriate frameworks for managing their credit risk by establishing a robust credit risk environment; a sound credit-underwriting process; and maintaining appropriate credit administration, measurement, monitoring, and recovery processes and functions”.
While the credit-risk measures focus on how banks assess and manage lending risks, the LCR requirement targets their ability to meet short-term financial obligations during periods of stress. Together, the measures address two critical areas of banking-sector resilience: the quality of banks’ credit portfolios and their capacity to maintain sufficient liquid assets.
The BoG has also urged banks to reinforce their fraud controls, cybersecurity measures, and technology-risk management as digital financial services continue to expand, reflecting growing exposure to technology-driven risks alongside the rapid adoption of digital banking and payment services.
Implementation and Outlook
The draft provides for a one-year pilot period following publication, during which banks would submit quarterly reports to the central bank using prescribed templates. Monthly reporting would be required after the pilot period. The BoG says it will consider all material comments received during the consultation and provide written explanations of how they were addressed, including whether they were incorporated into the final directive.
How the BoG defines HQLA will shape the practical impact of the rule. If government securities count heavily, the requirement could push banks to hold more of them at a time when Treasury bill yields have fallen to multi-year lows, potentially affecting bank profitability and lending capacity. Treasury desks will also need new systems to measure and report the ratio. The full scope of the impact will only become clear once the final directive is published.