

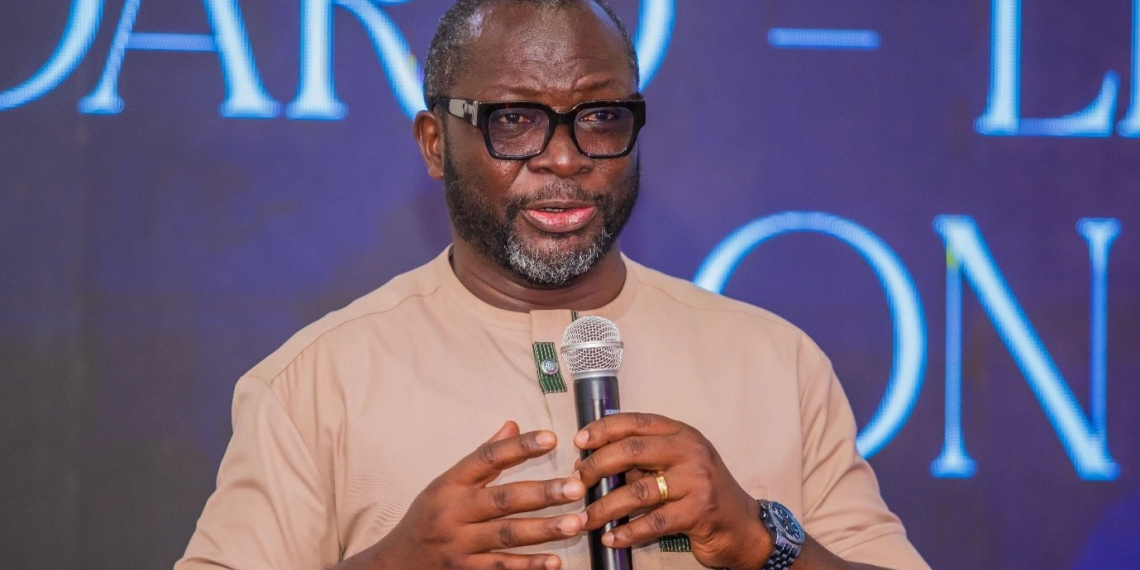
The Ghana Association of Banks (GAB) has called for a fundamental overhaul of the country’s credit architecture, warning that simply directing banks to increase lending to small and medium-sized enterprises (SMEs) will not work unless the broader risks facing businesses are systematically addressed.
Speaking at the Chartered Institute of Bankers Ghana (CIB Ghana) Post-MPC Policy Seminar in Accra, GAB President John Awuah said banks are willing to provide more financing to SMEs, but structural weaknesses in storage, distribution and market access continue to undermine borrowers’ ability to repay loans.
“Before we start talking about lending to SMEs, we need to ensure that the credit chain is properly enclosed,” Mr. Awuah told an audience of bankers, policymakers and industry leaders.
The Tomato Paradox
Mr. Awuah used agriculture as a stark illustration of the systemic risk problem. He described how farmers can obtain financing, increase production, and still default on their loans because of inadequate systems to store and market their produce.
“We saw tomatoes, heaps of them by the roadside,” he said. “Locked in the farm gates, glut. And for that reason, farmers were losing money”.
This scenario, he argued, creates a situation where a bank can provide financing for increased production, only for the resulting produce to go to waste—leaving the borrower unable to repay.
“You cannot have a situation where a bank gives a farmer one million Ghana cedis… all of a sudden can do 10 acres. And that’s 10 acres and the farm produce gets rotten. And then there’s default,” Mr. Awuah said.
The problem is well-documented. Ghana’s tomato sector routinely experiences seasonal gluts followed by shortages, with post-harvest losses ranging from 20% to 50% depending on the season and location. Farmers in areas like Asante Akyem Agogo have repeatedly appealed for buyers as bumper harvests overwhelm limited storage infrastructure, forcing distressed sales or outright losses.
NPL Ratio Decline: A False Signal?
Mr. Awuah’s comments come amid broader efforts to reduce the banking sector’s non-performing loan (NPL) ratio while expanding credit to the economy. The Bank of Ghana (BoG) has set a target to reduce the sector-wide NPL ratio to 10% by December 2026, down from 16.1% recorded in June 2026.
However, the GAB President cautioned that the decline in the NPL ratio should not automatically be interpreted as an improvement in borrowers’ repayment behaviour.
“There is a balance of risk, so the ratio could fall simply because the overall loan book is expanding faster than the stock of non-performing loans,” he explained. “The question we should be asking is, does it necessarily mean that repayment culture or credit performance culture has improved?”
Bank of Ghana data supports this concern. Gross loans and advances increased by 39.4% year-on-year to GH¢124.3 billion at the end of June 2026, compared with just 5.5% growth a year earlier. The NPL stock declined to GH¢19.9 billion from GH¢20.7 billion over the same period, but the rapid expansion of the loan book has contributed to the ratio’s mathematical decline.
Mr. Awuah stressed that high NPLs pose a significant risk to banks because they can result in the loss of the principal amount lent, rather than merely the interest income expected from the loan.
“If two, just two of those loans go bad, you are not just losing the interest, you are losing the principal amount,” he said.
The data reveals a particularly troubling trend in agriculture. While asset quality improved across most sectors, the NPL ratio for agriculture, forestry and fishing increased from 51.6% to 54.7% in February 2026, and further to 65.1% by June 2026. This means nearly two-thirds of all agricultural loans in Ghana are not being repaid on time.
Dysfunctional Commodity Exchange and Warehouse Receipts
Mr. Awuah also raised concerns about the effectiveness of mechanisms intended to support agricultural financing, including the Ghana Commodity Exchange and warehouse receipt systems.
“We have commodity exchange, which to me, for all intents and purposes, is dysfunctional. Warehouse receipts don’t work in this country,” he said.
The warehouse receipt system, designed to allow farmers to use stored produce as collateral for loans, has struggled with implementation challenges including inadequate insurance coverage, poor storage conditions and limited participation by financial institutions. The disconnect between the warehouse receipt system and the Ghana Commodity Exchange has further undermined the framework’s effectiveness.
The SME Financing Gap
The stakes are enormous. SMEs account for approximately 92% of all businesses in Ghana and contribute about 70% of GDP, according to data from the Ministry of Finance and United Nations Ghana. Yet the annual financing gap for SMEs is estimated at $4.8 billion—one of the most severe on the African continent.
Research conducted by Development Bank Ghana, the University of Ghana Business School and the Bank of Ghana reveals that only about 35% of MSMEs currently have access to bank financing.
The barriers are multifaceted. A survey by the CIB Ghana found that about 72% of banking sector respondents expressed high confidence in economic stability, and 89% anticipated improved lending appetite over the next quarter. However, structural challenges persist, including high collateral requirements—sometimes up to 120% coverage—extended credit approval periods ranging from 15 to 18 months, and high rejection rates for SMEs, especially in manufacturing and value addition.
Mr. Awuah acknowledged that certain lending requirements are regulatory obligations designed to safeguard depositors’ funds. He noted that Ghana has one of the highest NPL ratios in the West African sub-region, hovering around 19% at one point, which forces banks to take a defensive posture toward individuals and businesses.
“The credit culture is bad. There’s default everywhere—from individual level to household to business,” he said at a separate engagement with the Ghana National Chamber of Commerce and Industry (GNCCI) earlier this year.
Call for Stronger Credit Architecture
Mr. Awuah called for improvements in Ghana’s credit architecture to allow banks to better differentiate borrowers according to their credit histories and risk profiles. He said stronger credit information would allow lenders to make more informed decisions about the amount of credit a borrower can access and the appropriate pricing of that credit.
“We need to improve the risk profile, not of the SME, but in the systemic profile of the risk,” he said.
The Bank of Ghana has signaled that it is exploring reforms to leverage digital transaction data as a form of credit history. With mobile money platforms processing 954 million transactions valued at approximately GH¢493 billion in June 2026 alone, the central bank sees an opportunity to build “credit rails” that would allow SMEs to use their transaction histories and payment patterns as evidence of creditworthiness, bypassing the need for traditional collateral.
Mr. Awuah maintained that banks are already supporting SMEs through dedicated programmes, but said more can be done if the broader risk environment is improved.
“If you lose the fight on lending to the SME, we’ve lost the economic fight,” he said. “Banks are lending to SMEs. But all I’m saying is a lot more can be done to deepen interest in that”.
The CIB Ghana Post-MPC Policy Seminar was held under the theme “Balancing Stability and Growth: Interest Rates Impact in Geopolitical Shocks,” bringing together representatives from the Bank of Ghana, Ministry of Finance, Association of Ghana Industries, Ghana Union of Traders’ Associations, and key banking institutions.